
Your real rewards rate is the dollar value of the rewards you actually pocket, divided by the dollars you spent to earn them, times 100. A card advertising “5% back” might deliver 5%, 2%, or nearly 0% — the difference is how you redeem.
Key takeaways
- Real rewards rate = (dollar value of rewards actually received ÷ total spending) × 100.
- Cash back rates are honest: 2% cash back is 2%. Points rates depend entirely on redemption — the same point can be worth 0.6 or 2+ cents.
- The most common published benchmark for transferable points, The Points Guy’s valuations, puts Amex Membership Rewards at 2 cents per point — but that’s a target, not a promise.
- Caps, category definitions, and unredeemed balances all pull your real rate below the headline rate.
- Run this math once a year; it takes ten minutes and often changes which card you reach for.
The formula
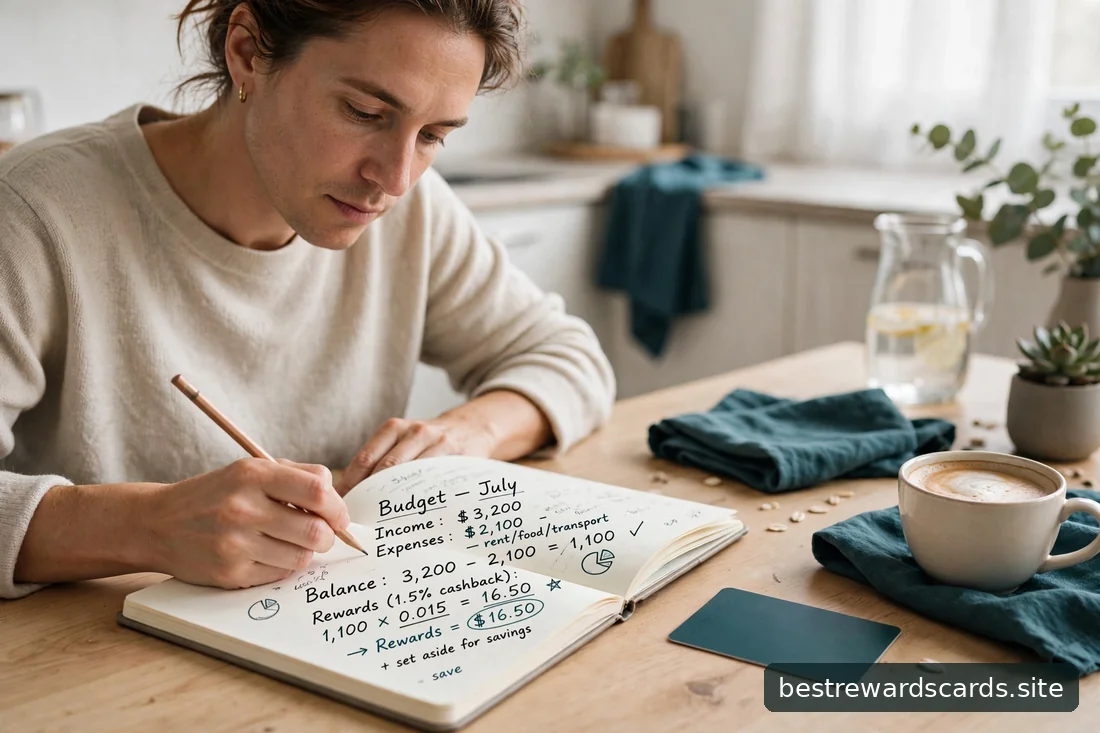
Real rewards rate = (value of rewards received ÷ amount spent) × 100
Two words matter: received and spent. Not points earned — points received as value. Not the headline earn rate — your actual spending. Everything in this article is about closing the gap between the marketing number and your number.
For cash back, “value received” is simple: dollars. For points and miles, you have to convert points to dollars first:
Cents per point = (dollar value of the redemption ÷ points used) × 100
Book a $300 flight with 25,000 points and you got 1.2 cents per point. Redeem those same 25,000 points for a $150 statement credit and you got 0.6 cents per point. Same points, half the value. This is why “how many points did I earn” is the wrong question. “What did I get for them” is the right one — and it’s the number that determines whether your card strategy is actually working.
Cash back: the easy version
Cash back is the only rewards currency where the advertised rate is the real rate — as long as you redeem it. A flat 2% card like the Citi Double Cash or Wells Fargo Active Cash pays 2% on purchases (the Double Cash splits it as 1% when you buy and 1% when you pay). Spend $20,000 in a year, redeem everything, and you have $400. Rate: 2.0%.
Category cards need one extra step because of caps. Take a card paying 5% on groceries up to $6,000 a year, then 1%. If you spend $8,000 on groceries:
- $6,000 × 5% = $300
- $2,000 × 1% = $20
- Total: $320 on $8,000 = 4.0% real rate, not 5%.
The headline said 5%; your rate is 4%. Caps are the quietest rate-killer in cash back. Whenever you compare category cards, compute the rate on your spending, not the card’s maximum.
Points: where the advertised rate lies
Points cards advertise earn rates (“3x on dining!”) but pay out in redemptions, and redemption values swing wildly. Using published data from The Points Guy’s April 2026 valuations of Amex Membership Rewards points as a benchmark:
- Transferring to airline or hotel partners: often around 2 cents per point — the benchmark valuation, achievable on good award bookings and beatable on great ones.
- Booking flights through Amex Travel: a fixed 1 cent per point.
- Booking hotels through Amex Travel: about 0.7 cents per point.
- Gift cards: 0.5 to 1 cent per point depending on the merchant.
- Pay with Points at checkout: 0.7 cents per point.
- Statement credit against charges: 0.6 cents per point.
Now apply the formula. A card earning 3x points on dining produces:
- 3 × 2.0¢ = 6.0% if you transfer to partners skillfully
- 3 × 1.0¢ = 3.0% if you book flights through the portal
- 3 × 0.6¢ = 1.8% if you cash out as statement credit
Same card, same spending, three wildly different real rates. Anyone quoting a points card’s “rewards rate” without naming the redemption method is quoting a fantasy. For a deeper dive on what drives point values, see our guide on how much credit card points are actually worth.
Worked example: one year, two cards
Meet a hypothetical spender: $12,000 a year on dining, $6,000 on groceries, $12,000 on everything else — $30,000 total. Two setups:
Setup A: one flat 2% cash back card. $30,000 × 2% = $600. Real rate: 2.0%. Ten seconds of thought per year.
Setup B: a 3x-on-dining points card plus a 2% card for the rest. Dining earns 36,000 points; the rest earns $360 cash back. Now the redemption decides:
- Transfer the points to an airline partner at ~2 cents each: $720 + $360 = $1,080 → 3.6% real rate.
- Book flights through the portal at 1 cent: $360 + $360 = $720 → 2.4% real rate.
- Take statement credits at 0.6 cents: $216 + $360 = $576 → 1.9% real rate — worse than the simple flat card.
This is the whole game in one table. The points card only wins if you redeem well. If you know you’ll cash out lazily, the flat-rate card isn’t the boring choice — it’s the higher-paying one. Our flat-rate cash back cards compared piece walks through which simple cards deliver that 2%.
The four things that shrink your rate
1. Spending caps. Covered above: any “up to $X” in the terms means your rate on spending above the cap drops to the base rate. Model your actual spend, not the cap.
2. Category definitions. “Groceries” usually means supermarkets — not Walmart, Target, Costco, or wholesale clubs. “Dining” usually covers restaurants but sometimes excludes bakeries, bars, or delivery apps depending on the merchant code. A purchase you thought earned 5% earning 1% instead is a silent rate cut.
3. Unredeemed and expired balances. Points sitting unredeemed are a 0% rate on that portion of your spending. Worse, some expire. Cash back you never redeem is money you earned and abandoned. Set a calendar reminder; this is the easiest rate boost available.
4. The annual fee. A fee is a direct subtraction from rewards received. $600 in rewards on a $95-fee card is $505 net on $30,000 of spending — a 1.68% real rate, not 2%. Always compute the rate after the fee. (Our transfer partners guide shows how moving points to airlines and hotels is usually what makes a fee worth paying.)
A 10-minute annual audit
Once a year, do this:
- Total your spending per card from the last 12 statements (most issuers show annual summaries).
- Total rewards received — dollars of cash back redeemed plus the dollar value of travel you booked with points.
- Divide. That’s your real rate per card.
- Compare each card’s real rate against a 2% flat-rate baseline. Any card underperforming it needs a better redemption strategy — or a downgrade to something simpler.
- Check the fee. Subtract each annual fee from its rewards and recompute. If a fee card’s net rate trails your no-fee cards, it’s not earning its keep.
Write the numbers down. Memory is generous to cards you like and harsh to cards you don’t; the spreadsheet doesn’t care about your feelings.
Putting your rate to work
Once you know your real rate, the next question is whether a different card would beat it. A 2% flat card is the benchmark most rewards cards have to clear — and many don’t once fees and weak redemptions are counted. If your audit shows you’re underperforming, our best rewards credit cards of 2026 roundup compares the current top options by spending profile, with the break-even math shown for each.
Frequently asked questions
What is a good credit card rewards rate?
For cash back, 2% flat is the practical benchmark — anything above 2% on uncapped spending is excellent. For points, a good real rate after redemption is 2–3%+ for engaged travelers who transfer to partners; under 2% means your redemption strategy needs work or a flat cash back card would pay more.
How do I calculate cents per point?
Divide the cash price of what you booked by the points you spent, then multiply by 100. A $450 hotel night for 30,000 points = 1.5 cents per point. Always use the price you would actually have paid, not the inflated rack rate.
Do welcome bonuses count in my rewards rate?
For year-one math, yes — but keep them separate from the ongoing rate. A big bonus can make a card’s first-year rate look amazing while its everyday rate is mediocre. Compute both: the first-year rate with the bonus, and the steady-state rate without it.
Why is my real rate lower than the advertised rate?
Usually one of four culprits: spending caps, purchases miscoded outside bonus categories, points redeemed at poor value (statement credits, gift cards), or an annual fee eating the margin. The audit section above finds which one.
Should I use a 2% flat card or a points card?
If you redeem points by transferring to airline and hotel partners for award travel, points usually win. If you redeem for cash, gift cards, or portal bookings at 1 cent, a 2% flat card usually wins with far less effort. Be honest about which redeemer you are.
This article is for education, not financial advice. Rewards programs change; verify current earn rates and redemption values with the issuer before applying. Kevin Park and Reward Radar don’t provide personalized financial recommendations.
Sources: The Points Guy — Amex points value, April 2026 valuations (2¢ benchmark; portal and non-travel redemption values); The Points Guy — Citi Double Cash review (1% buy + 1% pay structure); issuer card pages for current earn rates.